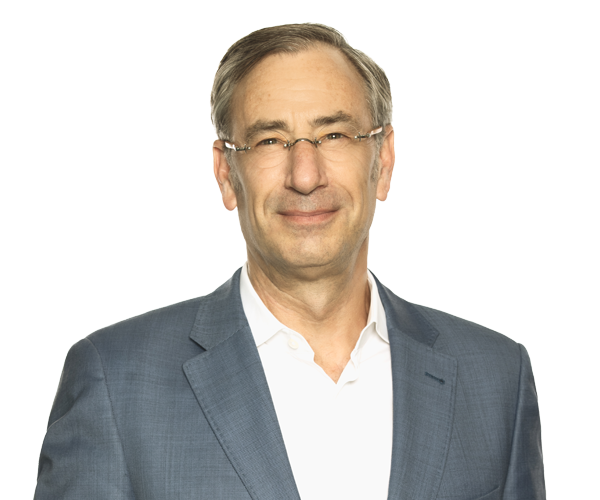
Harold Geller
Partner
There is more than one way to try to recover an investment loss.
If you believe bad advice, advisor misconduct, an unsuitable investment or a financial institution contributed to your loss, the next question is usually:
What can I actually do about it?
There is no single recovery process that is right for every investor.
Some matters can be resolved through a complaint to the financial firm. Others may be appropriate for the Ombudsman for Banking Services and Investments, known as OBSI. Some require negotiation, arbitration or litigation. If many investors were affected by the same conduct or investment, a group claim or class action may also need to be considered.
Led by Harold Geller and Matthew W. Taylor, the Sotos Investor Protection Group helps Canadians understand the available recovery options and choose a path that fits their circumstances.
The right approach may depend on:
You do not need to choose a process before speaking with us.
We can help you understand the options first.
Start by identifying the problem.
Ask yourself:
Then preserve the documents you already have.
Helpful records may include:
You do not need a complete file before asking for legal advice.
Record when you first became concerned, whether you have already complained and what response you received. Note whether other investors may be affected.
Read more about Bad market or bad advice?.
Maybe, but there are risks.
A complaint to the investment dealer, bank or financial institution gives the firm an opportunity to investigate what happened and respond. These complaints are often treated as an opportunity to delay, confuse, cherry-pick and then deny. The internal processes are not fair; they are an opportunity for the financial firm to strengthen their defence, fix their records, get you to make admissions where you do not know the significance of the admission.
This is not a straightforward or balanced process. Be warned!
Your complaint should clearly explain:
The firm may:
For some external complaint processes, complaining to the firm first is required.
Not automatically.
Before accepting an offer, consider:
Make sure you see the settlement papers before you agree. Often after agreement the firm will add unfair requirements like overly broad Non-Disclosure Agreements or limiting your right to sue other parties who harmed you.
A settlement may provide a quicker resolution, but signing a release can affect your ability to pursue the matter further.
The Ombudsman for Banking Services and Investments, or OBSI, is an independent dispute-resolution service for consumers and participating financial firms.
OBSI can only consider a small section of the financial advice process. OBSI can investigate complaints involving participating investment firms and banks after the consumer has first complained to the firm. That’s it. That’s all. They cannot investigate financial planning, estate planning, retirement planning, tax planning, insurance recommendations and negligence.
For investment firms, consumers can generally go to OBSI if they remain dissatisfied after receiving the firm’s final response or if the firm has not responded within the applicable complaint-handling period.
OBSI can recommend compensation of up to $350,000 for a single complaint, but that would be exceptional if not the first time. Its recommendations are not legally binding in the same way as a court judgment, although OBSI can publicly identify a firm that refuses to follow a recommendation. Often firms use an OBSI recommendation as a starting point to then bargain you down.
No.
Consumers can use OBSI without a lawyer. With an OBSI complaint, expect the dealer to have lawyers or trained specialists at work – the playing field is not level, it’s slanted to the defence by design.
Often you have to describe an OBSI complaint using technical terminology or OBSI will not investigate the root cause, it will only investigate what they deem you to have complained about. You don’t know the root cause, chances are that you will not know how to frame your complaint in a way to fully engage OBSI’s investigation and protect your rights.
However, legal advice may still be useful where:
OBSI does not provide legal advice.
OBSI generally requires the consumer to have raised the complaint with the firm within six years after the consumer knew or should have known about the problem. This is a theoretical six years. If you are more than two years from the discovery of your claim, then most dealers will frustrate OBSI’s recommendation and force you into the courts – where the 2 years limitation period applies. The six years limitation is a notion, not a practical time frame.
After receiving the firm’s final response, the consumer generally has 180 days to bring the complaint to OBSI.
Those are OBSI’s own time limits. They are not necessarily the same as the legal limitation period for a lawsuit.
Yes.
Many financial disputes are resolved through negotiation. Usually not before many hoop jumping steps. In most cases, the investment firm will make you start a lawsuit, disclose all documents, and attend oral discovery before making low end offers. Attrition and high costs are common tools to divert legitimate claims.
A lawyer may communicate with the advisor, dealer, bank, insurer or its lawyers and attempt to reach a resolution without starting or completing a court proceeding.
Negotiation may involve questions such as:
A negotiated resolution can sometimes save time and cost. A fair negotiated settlement almost always follows complicated hoop jumping.
It also gives the parties more control over the outcome than a decision imposed by a court or arbitrator.
However, a settlement usually requires the investor to sign a release ending some or all of the claims.
The terms should be understood before anything is signed.
Mediation is a structured settlement process.
A neutral mediator helps the parties discuss the dispute and explore whether an agreement can be reached.
The mediator does not decide who wins.
Instead, the mediator helps the parties:
Mediation can be useful where the parties disagree strongly but still want to avoid the cost and uncertainty of a full hearing or trial.
A successful mediation ends with a negotiated settlement.
If no agreement is reached, the parties may continue with another recovery process.
Arbitration in investment loss cases is rare. Arbitration is a private dispute-resolution process.
Instead of having a judge decide the case in court, the parties present their evidence and arguments to an arbitrator.
The arbitrator then makes a decision.
Depending on the circumstances, arbitration may offer:
However, arbitration also has disadvantages.
There may be:
CIRO maintains an arbitration program for eligible investment disputes, although it is used relatively infrequently. A proposal to reform it for greater fairness is before CIRO. CIRO is a member organization. The investment firms are the members. CIRO members oppose the reforms.
Whether arbitration makes sense depends on the agreement, size of the claim and available alternatives.
Civil litigation may be appropriate when:
A court claim may involve allegations such as:
Litigation may allow the parties to obtain documents, question witnesses and ask a court to decide the dispute.
It can also take time and involve significant cost and uncertainty.
For that reason, starting a lawsuit does not necessarily mean the matter will ultimately proceed to trial.
Many court cases are resolved through negotiation or mediation before a trial takes place.
Sometimes several investors have losses involving:
Those investors may have common legal and factual issues.
In some circumstances, it may make sense to coordinate the claims rather than have each investor proceed entirely alone.
A coordinated approach may allow investors to:
A group claim is not necessarily the same as a class action.
The appropriate structure depends on how similar the investors’ claims are and whether individual issues remain important.
A class action may be appropriate when a large group of people has been harmed by the same or similar conduct and important issues can be decided together.
Examples could involve:
A proposed class action must satisfy the legal requirements for certification before it can proceed as a class proceeding.
Not every investment loss is suitable for a class action.
Individual questions about what an advisor told each investor, the investor’s financial circumstances or whether a particular recommendation was suitable may sometimes make individual claims more appropriate.
The Sotos Investor Protection Group can assess whether the issue appears better suited to:
For questions about institutional participation, see our services for institutional investors and family offices.
They are different processes.
OBSI is generally:
Its recommendations are not legally binding in the same way as a court judgment.
A lawsuit:
Using OBSI does not automatically mean that you give up the right to take legal action afterward if you do not accept the outcome. OBSI specifically states that consumers retain some of their legal rights, subject to applicable limitation periods and other legal considerations.
The right choice depends on the claim.
This is one of the most important questions to ask.
Legal claims are subject to limitation periods.
Those deadlines vary by province and by the circumstances of the claim.
Starting an internal complaint with a financial firm does not necessarily stop the legal limitation period from running. It does not stop the time running for the financial advisor, almost always the key person to name in a lawsuit.
OBSI has a specific process that may suspend on a limited basis a legal limitation period through a tolling agreement once the OBSI investigation formally begins and the required consent is received. OBSI states that the limitation clock generally begins running again 30 days after its final letter or the end of the investigation.
That does not mean every complaint automatically stops every legal deadline.
If a significant amount of money is involved, consider obtaining legal advice early rather than waiting until the complaint process is finished.
There is no universal answer.
A lawyer may consider:
A smaller claim may not justify an expensive court process.
A larger or more complex claim may require litigation or another formal process.
Account documents, emails, recorded instructions, advisor notes and regulatory records may affect which process makes sense.
A claim against one advisor may require a different approach from a claim involving a dealer, bank, fund manager and several other parties.
A repeated problem may justify a coordinated claim or class action.
Some cases cannot be properly investigated without obtaining records from the other side or questioning witnesses.
The amount of time remaining before a limitation period expires can affect the available choices.
A recovery strategy should make economic sense.
The cost, time and risk involved should be considered against the amount that may realistically be recovered.
Harold Geller brings more than 30 years of investor-protection, financial-services and complex-product experience.
Matthew W. Taylor brings complex investment, securities and class action litigation experience, particularly where losses affect many investors or involve several potential defendants.
You can complain to the firm yourself.
However, speaking with a lawyer first may be useful when the loss is significant, the issues are complex or you are concerned about a legal deadline.
A lawyer can also help you understand what information to include and how a proposed settlement could affect other rights.
OBSI does not charge consumers a fee to use its service.
You also do not need a lawyer to make an OBSI complaint.
OBSI can currently recommend compensation of up to $350,000 for a single complaint.
Potentially.
OBSI states that consumers do not give up their right to pursue legal action simply because they use its process.
Legal deadlines and the effect of any settlement or release must still be considered.
No.
Many disputes are resolved through complaints, OBSI, negotiation, mediation or settlement.
Court is one option, not the only option.
It depends on how similar your claim is to the claims of other investors.
Some investment disputes depend heavily on individual advice and circumstances. Others involve common conduct affecting a large group.
We can assess which structure appears appropriate.
You do not need to calculate the final legal loss before contacting us.
Account statements, transaction histories and other records can help determine the amount and cause of the loss.
Not necessarily.
Legal deadlines can continue while complaints are being handled. Obtaining advice early can help you understand whether waiting could affect your options.
A lawyer from the Sotos Investor Protection Group will review the information you provide and identify the main legal and financial issues.
We assess which processes may be available and whether there are important deadlines or strategic considerations.
We will explain the potential advantages, disadvantages and next steps so that you can make an informed decision.
If further legal work is recommended, we will explain the proposed scope and fees before you decide whether to proceed.
Contact Harold Geller or Matthew W. Taylor directly, or request a confidential case assessment using the form below.
Partner

Senior Associate
Tell us what happened or what concerns you, who was involved and what you would like help with.
Start with what you know and the documents you have. You do not need to have every document ready before contacting us.