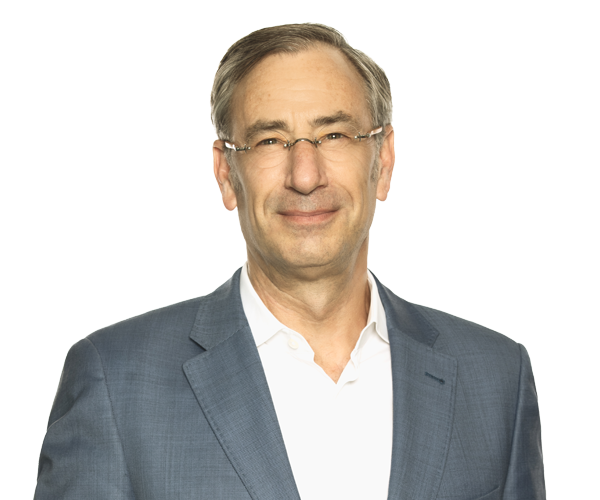
Harold Geller
Partner
When financial advice leads to loss, we help you understand what happened and what you can do next.
If you lost money, cannot access an investment, do not recognize activity in your account, are surprised by a request for further life insurance premiums, or had a life insurance claim denied, we can help determine whether something went wrong and whether there may be a path to recovery.
Led by Harold Geller and Matthew W. Taylor, the Sotos Investor Protection Group represents investors, policyholders, beneficiaries and families across Canada in investment-loss, unsuitable-advice, financial-advisor misconduct and life-insurance disputes.
Harold has more than 30 years of investor-protection, financial-services and regulatory experience and has assisted more than 1,500 Canadians with financial-loss claims. Matthew brings complex investment, securities, professional-liability and class action litigation experience. Together, and supported by Sotos’ broader litigation and class action teams, they can assess both individual claims and situations affecting larger groups of investors.
You may have lost money in an investment that was described as safe. You may be unable to withdraw your savings. Your account may show trades or information that you do not recognize. An older family member may have been financially exploited. A life insurance policy that was supposed to be “paid up” or be permanent and is not. A life insurance claim may have been denied when your family needed it most.
You do not need to know the legal term for what happened or have every document ready before contacting us.
Tell us what you were told, what happened and what you have lost or cannot access. We can help you understand your options and decide what to do next.
Not every investment loss means that someone did something wrong.
Markets can fall. Investments involve risk. Even an appropriate investment can lose value.
A closer review may be worthwhile, however, when what happened does not match what you were told, what you understood or what was appropriate for your circumstances.
You may want to speak with an investor protection lawyer if:
One warning sign does not prove that you have a legal claim.
But you should not dismiss serious concerns simply because an advisor or financial institution says that the loss was caused by the market.
Start with what you know. We can help investigate the rest.
Start with the problem you are facing.
Was the investment wrong for your needs?
An investment in stocks and bonds or in life insurance can be legitimate and still be unsuitable for you.
We review losses involving investments and strategies that may not have matched the investor’s:
Concerns may also arise when too much of a portfolio was placed in one product, company, manager, sector or high-risk strategy.
Learn About Unsuitable Investment Advice and Investment Loss Claims
Did your advisor act without your informed approval?
You trusted your financial advisor, portfolio manager or investment firm to understand your needs, follow your instructions and explain what was being recommended.
Warning signs may include:
We assess both the individual advisor’s conduct and whether the firm responsible for supervising the account may also bear responsibility.
Learn About Financial Advisor Misconduct and Negligence
Is your money locked up or tied to a product you do not understand?
Private and alternative investments can be difficult to understand, value and sell. Often they are sold as “not correlated to the markets”, but then move with the markets during major market swings.
Some investors only discover the risks after withdrawals are stopped, distributions are reduced or the reported value of the investment falls.
We review concerns involving:
The fact that an investor qualified to purchase a complex product does not automatically mean the product was suitable for that person.
Learn About Private, Gated and Complex Investments
Were you deceived, or did a financial institution fail to protect your account?
Investment fraud can involve a completely false investment, misleading information about a real product, unauthorized activity or misuse of investor funds.
The person who committed the fraud may not be the only party responsible.
An investment dealer, bank or financial institution may also have failed to:
Even if the dealer was not complicit in the fraud, it likely is still responsible for giving you your money back.
We assess both the immediate wrongdoing and whether another party may have contributed to the loss.
Learn About Investment Fraud and Dealer Responsibility
Are you worried that an older or vulnerable person was financially harmed?
Financial abuse can involve a family member, caregiver, attorney under a power of attorney, financial advisor, insurance agent or another person in a position of trust.
Warning signs may include:
Executors and estate trustees may also discover questionable financial activity after someone has died.
Learn About Elder Financial Abuse and Vulnerable Investor Claims
Was a life insurance claim denied, or was the wrong product sold?
A denied life insurance claim can leave a family facing financial pressure while it is also dealing with a death.
We represent policyholders, beneficiaries and families in disputes involving:
An insurer’s denial does not necessarily end the matter.
Did you get an unexpected demand for more money to keep your life insurance policy in force?
A demand for further funds can be punishing. These are common in a high-risk type of life insurance known as Universal Life Insurance sold on a Yearly/Annual Renewable Term basis. Complex? Yes, and often toxic. What are your options? Why were you not warned? We can help.
There is no single recovery process that is right for every investor.
The best path may depend on what happened, who was involved, how much was lost, what evidence is available and whether other investors were affected.
Possible options may include:
You may be able to complain directly to the bank, investment dealer, advisor’s firm, insurance company or other financial institution.
The firm may investigate the account, respond to your concerns and make a settlement offer.
While the company will likely delay, cherry-pick, and deny your concerns, if you opt for the OBSI complaint route, then you must first jump through this hoop. Take care, the companies use this process to reduce claims by wearing you out or wearing you down and almost never offer more than token payments, even in the clearest of cases.
The Ombudsman for Banking Services and Investments, known as OBSI, reviews unresolved complaints involving participating banks and investment firms.
OBSI can be one route to compensation, but it is not always the only option. OBSI lacks binding authority, has limited review abilities, and has a limited monetary threshold for recommending money be paid to you.
Some claims can be resolved through direct negotiation or mediation without a full court proceeding. More often, the companies will not enter into good faith negotiations until after they have made you jump through hoops within a court claim.
A negotiated resolution may reduce time, cost and uncertainty.
Some investment agreements or relationships may provide for arbitration.
Arbitration is a private process in which a neutral decision-maker hears the dispute.
A court claim may be appropriate when the loss is significant, the issues are disputed or another recovery process is not suitable.
When many investors have been affected by the same type of investment, advice or conduct, a coordinated group claim or class action may be more effective than separate claims.
Legal deadlines can continue while an internal, regulatory or ombudsman complaint is being handled. OBSI’s so-called Tolling Agreements DO NOT freeze the legal deadlines against your advisor, only against the member firm (the company). Do not assume that starting a complaint automatically protects crucial legal rights.
We can help you compare the available processes before you decide what to do.
The Sotos Investor Protection Group reviews potential claims where investors may have experienced similar losses arising from the same type of financial product, advice or conduct.
Our current work includes reviewing claims involving:
We are reviewing potential claims involving investors whose money is locked up, has been written down or was placed into products that were riskier than they understood.
The review includes concerns involving private credit, exempt-market products, alternative investments, mortgage investment products, margin, leverage, short selling, concentrated portfolios and other investments that are difficult to redeem.
Financial-loss claims often require more than general litigation experience.
The lawyer must understand how financial advisors, investment firms, insurance companies and complex products operate. The lawyer must also be able to pursue the claim through negotiation, an ombudsman process, litigation or a proceeding involving a larger group of investors.
Harold Geller and Matthew W. Taylor bring these two forms of experience together.
Supported by Sotos’ broader litigation and class action teams, they can assess both individual claims and situations affecting larger groups of investors.
Partner
Harold has more than 30 years of experience representing investors, policyholders and beneficiaries in financial-loss claims.
His work includes:
Harold has assisted more than 1,500 Canadians with financial-loss claims.
He has also served on investor and consumer advisory bodies connected with:
Harold is known for explaining complicated financial issues clearly and helping clients make informed decisions about their options.
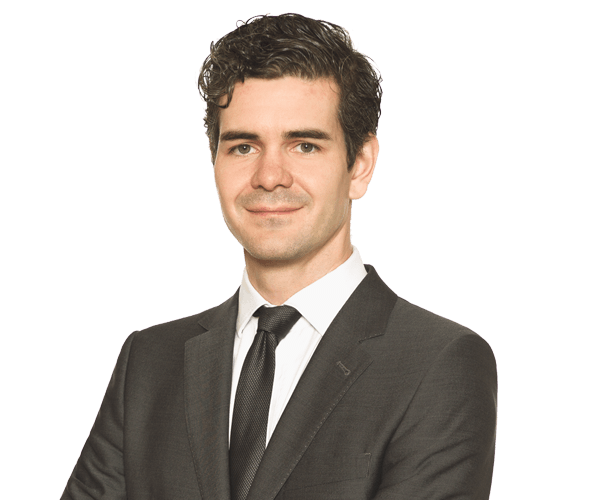
Senior Associate
Matthew represents plaintiffs in complex investment, securities, professional-liability and class action litigation.
His experience includes:
Matthew has appeared before the Court of Appeal for Ontario, the Ontario Superior Court of Justice and the Commercial List.
He writes about securities law and serves as a supervising lawyer at the Osgoode Hall Law School Investor Protection Clinic.
Matthew’s complex litigation experience strengthens the group’s ability to consider both individual and collective recovery options.
Harold and Matthew are supported by Sotos’ broader litigation and class action teams.
This allows the Investor Protection Group to assess different routes to recovery, including:
Possibly.
A market loss alone does not automatically create a legal claim. A claim may arise, however, when the loss was caused by unsuitable advice, negligence, misleading statements, unauthorized activity or misconduct.
The main question is whether the advice and activity in your account were appropriate for you and met the standards that applied.
An investment may have been unsuitable if it did not fit your personal and financial circumstances.
Relevant factors may include your:
An investment that was suitable for someone else may not have been suitable for you.
A signed form is relevant, but it may not tell the whole story.
A review may consider:
A gated or frozen investment restricts your ability to withdraw or redeem your money.
A key question is whether that possibility was properly explained and whether an illiquid investment was appropriate given your need to access your capital.
You do not necessarily have to wait until the investment becomes worthless before seeking advice.
The Ombudsman for Banking Services and Investments is an independent service that reviews unresolved complaints involving participating banks and investment firms.
You can use OBSI without a lawyer. However, OBSI is not always the only recovery option, and separate legal deadlines may also need to be considered.
Yes.
Once you know or should know that your advisor or their firm was negligent, then if you have any losses your time for suing is running. In Ontario you have two years to start a lawsuit. Wait one day to long, and your rights are gone. Do not wait for the losses to crystallize or for the exact calculation of the losses. Move to protect your rights as soon as possible.
A concern may exist before an investment becomes worthless, especially if:
Yes.
We review denied, delayed and disputed life insurance claims, as well as concerns about insurance advisor errors and unsuitable insurance products.
Financial-loss claims are subject to limitation periods.
The deadline may depend on where you live, what happened and when you knew or should have known that your loss may have been caused by unsuitable advice, negligence or misconduct.
Complaining to a financial firm, regulator or ombudsman does not automatically stop a legal limitation period, with a limited exception for the ombudsman. Obtaining legal advice promptly can help you understand the deadline and preserve your options.
You do not need to prepare a legal argument, calculate your legal damages or locate every document before contacting us.
Tell us:
You explain what happened in your own words.
You do not need to know the legal terms or have every document ready.
A lawyer from the Sotos Investor Protection Group will review the information you provide.
We may consider the advice, product, account activity, risk information, disclosure, supervision, losses and available records.
If more information is needed, we will explain which documents may be helpful.
We will explain whether the matter appears to require further assessment and which recovery options may be available.
If further legal work is recommended, we will explain the proposed scope, next steps and fees before you decide whether to proceed.
Contact Harold Geller or Matthew W. Taylor directly, or request a confidential case assessment using the form below.
Partner
Senior Associate
A serious financial loss can affect your retirement, your family and your sense of security.
Start with what you remember and the documents you have.
We can help you understand what happened and whether there is a path forward.