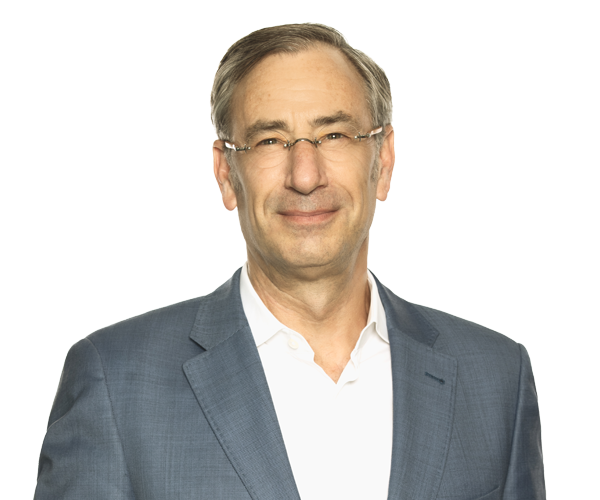
Harold Geller
Partner
Was the investment wrong for your needs?
You may have been told that your loss was simply caused by the market.
Sometimes that is true. Markets rise and fall, and even an appropriate investment can lose value.
But some losses happen because the investment or strategy should not have been recommended to that investor in the first place.
Led by Harold Geller and Matthew W. Taylor, the Sotos Investor Protection Group helps investors determine whether financial advice, an investment recommendation or an overall strategy may have contributed to their losses.
An investment may have been unsuitable if it did not fit your:
You do not need to know whether your advisor broke a rule before contacting us.
Start with what you were told, what you understood and what happened afterward.
An investment can be legitimate and still be wrong for you.
An investor with stable income, substantial assets and many years before retirement may be able to accept risks that would be inappropriate for someone who relies on investment income, needs access to savings or cannot afford a significant loss.
The question is not only whether an investment had the potential to make money.
The question is whether the recommendation made sense for you.
A suitability review may consider:
Your circumstances can also change.
Advice that may once have been suitable can become unsuitable after retirement, illness, job loss, divorce, an inheritance or another major life event.
Read more about Bad market or bad advice?.
The advice may deserve a closer review if:
One warning sign does not prove that the advice was improper.
But several warning signs together may suggest that the loss was not simply caused by normal market risk.
Keep the account records and communications that show what was recommended and what you were told. Note the investment, the advisor and when you first became concerned.
Two concepts often matter when assessing unsuitable investment advice: Know Your Client and Know Your Product.
Before making recommendations, an advisor should understand relevant information about you.
That includes more than asking you to select a label such as “conservative,” “balanced” or “speculative.”
Your advisor may need to understand your:
Concerns may arise if:
An advisor should also understand the investments being recommended.
A complex product may involve risks relating to:
If an advisor did not properly understand the product, the advisor may not have been able to determine whether it was right for you or explain its risks clearly.
Your account records may say that you were comfortable taking more risk than you remember discussing. Often advisors increase your recorded risk tolerance to sell you their favourite securities or funds that pay them more for the sale. These are serious breaches.
A risk profile can matter because it may be used to justify the investments recommended to you.
A review may consider:
A document saying that you were a “speculative” investor does not necessarily end the analysis.
A recommendation may deserve review if you were told:
The issue is not simply whether a document somewhere mentioned risk.
A review may also consider what was explained, what you understood and whether the recommendation was appropriate despite those risks.
Concentration can increase the impact of a loss.
A portfolio may deserve closer review where a large percentage of the investor’s savings was placed into:
Diversification does not eliminate investment risk, but excessive concentration may expose an investor to losses that were inconsistent with their needs.
Borrowing can magnify both gains and losses.
A leveraged strategy may leave an investor dealing with:
A review may consider whether you understood the additional risks and whether borrowing to invest was appropriate for your finances and ability to withstand loss.
No.
Being legally eligible to purchase a particular investment does not necessarily mean that the investment was suitable for you.
An accredited investor may still:
Suitability depends on the investor’s actual circumstances, not simply whether the investor met a financial threshold.
Depending on the facts, a claim may involve:
A firm may have responsibilities relating to:
Possible options may include:
The appropriate route depends on the amount lost, the evidence, the parties involved and applicable legal deadlines.
Harold Geller brings more than 30 years of investor-protection, financial-services and complex-product experience.
Matthew W. Taylor brings complex investment, securities and class action litigation experience, particularly where losses affect many investors or involve several potential defendants.
Possibly.
A market loss alone does not automatically create a claim. A potential claim may arise where the recommendation was unsuitable, important risks were not clearly explained or the advisor otherwise failed to act properly.
Approval can be relevant, but the question may also include whether you understood what was being recommended, whether the risks were properly explained and whether the investment was suitable for you.
A signed form matters, but it may not tell the whole story.
A review may consider who completed the form, whether it was accurate, whether it was complete when signed and whether it matched what you actually told the advisor.
Advice may need to change when your circumstances change.
Retirement, illness, divorce, job loss, inheritance or a new need for income or liquidity may require a different strategy.
No.
Account statements, transaction records and other documents can help determine the amount and cause of a loss.
You may be able to complain directly to the firm, but legal deadlines can continue while a complaint is being reviewed. Early legal advice can help you understand your options.
Contact Harold Geller or Matthew W. Taylor directly, or request a confidential case assessment using the form below.
Partner

Senior Associate
Tell us what happened or what concerns you, who was involved and what you would like help with.
Start with what you know and the documents you have. You do not need to have every document ready before contacting us.